

A research database for brand failure. A new Brand Autopsy every week. Every autopsy comes with a dated prediction, and every prediction is scored against the same framework.

RELATED POSTS
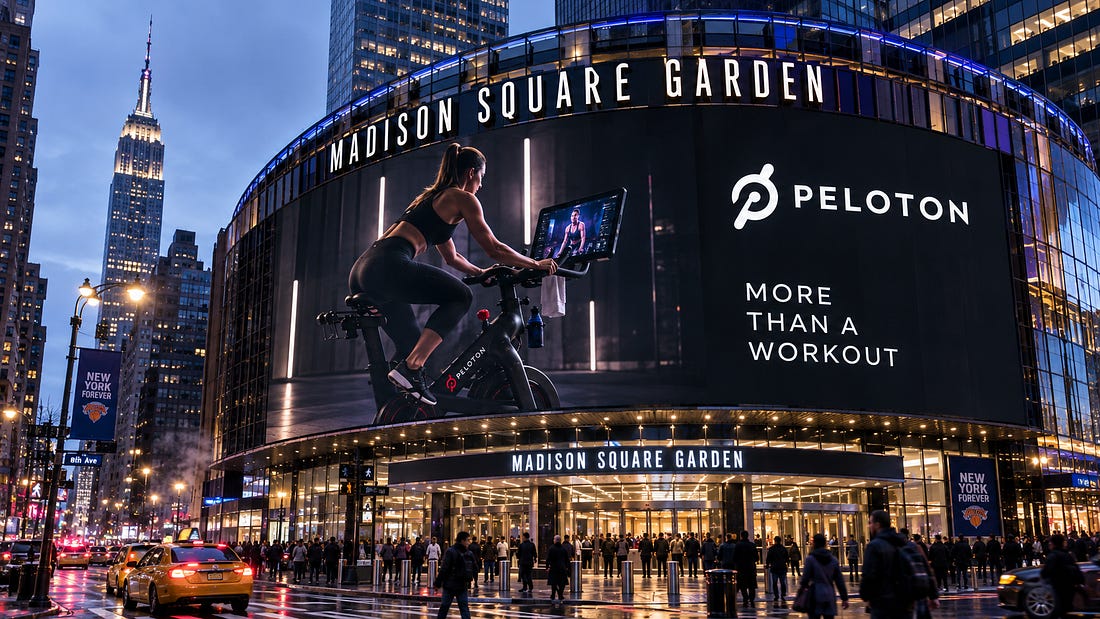
Why would anyone pay almost $2,000 for a bike? Go ahead. Try to answer that without lying to yourself. You can’t. I did the math, and I still don’t believe this is real. The Bike costs $1,695. The Bike+ costs $2,695, and neither price includes tax, shoes, or the mat you didn’t even know you needed. That’s just the cover charge. After that, you pay $49.99 a month, forever, just to use the classes. Stop paying the monthly fee and the bike doesn’t break. It just turns into a regular stationary bike with a screen stuck on it, the kind you can buy for way less money. The fee is the whole reason to buy this bike instead of a cheaper one. Skip it, and you just paid $1,695 for a very expensive coat rack that happens to pedal. Now think about what you already pay for every month: $19.99 for Netflix, $12.99 for Spotify, $14.99 for Apple TV+. Just those three add up to $47.97. One Peloton subscription costs more than that, all by itself. Add Amazon Prime at $14.99 and the four together come to $62.96, still not much more than Peloton alone. One bike, stuck in one room, costs more each month than three of the four things you already use on every device you own. Check the math yourself. I’ll wait. And don’t you dare call it an investment. I checked that too. Peloton won’t even tell you how long the bike is supposed to last. That should already tell you something. Repair shops and reviewers who track this kind of thing say 5 to 10 years, with good care. The free warranty only covers 12 months. Want it covered longer, up to 4 years? That’s roughly another $170 to $270, on top of what you already paid. Skip it, and a broken screen alone can cost roughly $750 to fix. Let’s call the bike’s life 7 years, right in the middle. Add the bike price to 7 years of the $49.99 fee and you get $5,894. That’s about $70 a month, every month, for seven years. A regular US gym membership costs about $50 a month. So this “investment” costs more per month than a real gym, and a gym doesn’t own you back. Quit a gym and you owe nothing. Walk away clean. Quit Peloton and you’re stuck with a machine in your room that you’re still paying to make useful. This story was picked by a group called the Unseen Billions. It’s a paid community. The members vote on which company I take apart next. I call them “the investigators,” because that’s exactly what they are. They don’t just pick the company. They get the full scorecard behind it, and they see what happens next, new filings, new numbers, whatever comes after I publish. The free version gives you this story. The paid version gets you the rest of it, as it happens. They picked Peloton. Here’s what I found when I went looking. Let’s look at who it’s actually for. I spent two weeks reading everything Peloton has filed with the government: yearly reports, earnings calls, all of it. I came out more confused than when I started. Peloton says its customer is rich, educated, lives in a city, and doesn’t have much free time. Sure. That description is basically Mr. Big, from the original “Sex and the City,” rich, educated, living in Manhattan, exactly the customer Peloton says it built this for. The reboot killed him off with a heart attack, on a Peloton, in the very first episode. I don’t buy that as an accident. Even the writers looked at the exact customer Peloton says it wants, put a Peloton in the room with him, and turned it into a joke about dying. Here’s the real question, and it has nothing to do with money. Plenty of rich people already own a Peloton. Money was never the wall. The real question is simpler and meaner than that: is this one thing, the bike plus the $49.99 fee, so much better than every other option that it’s worth picking? A trainer. A gym. A free workout app. More and more people are answering no. That shows up in Peloton’s own numbers, and I’ll get to those in a minute. So here’s where all of it leaves me: no real answer for who this company thinks its customer is, and no proof that person still exists in 2026. That’s what the investigators sent me to find out. The ThesisBrittain Ladd helped me build this thesis. He shared his research with me. Ladd is a business strategist, someone who studies how companies make big decisions and where those decisions go wrong. He has worked in supply chain and logistics, meaning how products get made and shipped, for companies like Dell, Amazon, Deloitte, Kroger, and Instacart. He also spent five years writing for Forbes about business and retail. According to Ladd, John Foley, Peloton’s founder and CEO, needed to go once it became clear he was betting that pandemic demand for home fitness equipment was permanent. Here’s his reasoning: pandemics, historically, last about 6 to 9 months. Foley believed COVID would last much longer than that. That belief is what pushed him to buy a manufacturing company so Peloton could build more bikes. Ladd calls that decision the kiss of death. Once COVID ended sooner than Foley expected, which it did, Peloton would be stuck with warehouses full of bikes nobody wanted anymore, while storage and shipping costs ate into the company’s money. Ladd also says he predicted something else: once gyms reopened, people would go right back to them, Peloton customers included. According to Ladd, Foley believed he had permanently changed how people liked to work out. Ladd says that belief was wrong too. According to Ladd, Foley should have done something different. He should have bought major gym chains instead, betting that gym memberships would bounce back hard once COVID ended. That move would have put Peloton right where the real demand was heading. It also would have let Peloton sell its own bikes and equipment inside the gyms it now owned. Here is my thesis, and what I think. Ladd explains the timing: what Foley should have seen coming, and what he should have done instead. I’m going to explain what’s underneath that. Not just whether Foley made the right call in 2020, but whether this product was ever worth what it costs in the first place. We go off Ladd here. Peloton didn’t misread the pandemic. Peloton misread what the pandemic meant. That difference matters a lot. Misreading the pandemic would just mean bad timing, a company caught off guard by how long COVID lasted. That’s not really what happened. Peloton watched people get locked in their homes for 18 months with nowhere else to go, and decided that was the new normal way people wanted to live. It wasn’t. It was just what happens when every gym in the country is shut down by law. Once you see it that way, everything else stops looking like a separate mistake. It’s the same mistake wearing different outfits. Buying a manufacturing company only makes sense if you believe the demand is permanent and you need more factories. Building piles of unsold inventory, extra bikes sitting around unsold, only happens if you built for a customer who was never coming back at that size. Charging a monthly fee on top of expensive equipment only works if people keep choosing home workouts over everything else, forever, the way they were forced to during lockdown. Even the customer Peloton describes in its own reports, rich, lives in a city, no free time, is really just a description of whoever happened to be stuck at home in 2021. None of this is actually new, either. It reminds me of being a kid, home sick from school, watching TV with my mom before Days of Our Lives came on at 10 o’clock. In between, there was always some ad selling exercise equipment, a bike, a stepper, a gadget with a name, promising it would change your life if you just bought it and kept paying. Different decade, different machine, same pitch. Peloton is that same ad. It just has a screen, an instructor, and a monthly fee bolted onto it now. There’s a second layer under all of this. The bike plus the subscription isn’t something most people actually want, even the ones who can easily afford it. There are a thousand other ways to work out right now: apps, YouTube, a regular gym, a running club, a personal trainer, equipment with no monthly fee attached at all. Someone with plenty of money looks at $1,695 plus a fee forever, next to a thousand options that don’t lock them in, and most of the time they walk away. The real issue is whether Peloton ever gave people a reason to pick this over everything else. It hasn’t. Say it plainer, for the exact customer Peloton claims to want. Price genuinely does not matter to someone living in Manhattan making that kind of money. Dyson sells a $700 vacuum, and people still buy it, because Dyson answered the question: it’s better made, it looks different, owning one means something. Peloton has never answered that question for its own customer. Why this bike, and not a cheaper one, or no bike at all? And what does someone get for staying loyal, for paying that fee every month for years, besides still being allowed to use the thing they already bought? Dyson gives people a reason to choose it and a reason to stay. Peloton has given its own richest, most likely customers neither. Every one of these decisions makes total sense if you still believe it’s March 2020. None of them make sense once you don’t. That gap, between what people at Peloton privately know now and how they’re still running the company, is what the rest of this story digs into. The BillBefore going further, here’s the actual cost, and it has three different answers that measure three different things. Mixing them up is how you get a number nobody can trust. The lost company value: roughly $47 billion. Peloton peaked at about $50 billion in January 2021. Today, September 2026, it’s worth about $2.2 billion, a drop of roughly 95%, one of the steepest falls of any pandemic-boom company. Every stay-at-home stock fell back to earth once the world reopened, but not by 95%. That’s the difference between a normal correction and a company actually falling apart. The single-day hit: about $2.5 billion, in hours. On January 20, 2022, Peloton announced it was halting Bike and Tread production over dried-up demand. The stock fell below its own starting price for the first time, wiping out roughly $2.5 billion in a single trading day. That’s the exact day the growth story ended. The ongoing leak: roughly $148 million a year, and still running. This is the number that matters most because it’s happening right now. Peloton’s paid subscriptions fell by 247,000 in fiscal 2026 alone, worth about $148 million a year at today’s $49.99 price, with guidance pointing to almost another 10% drop next year. Why: 2.2% of paying members cancel every month and rising, roughly a quarter of all subscribers a year, people who already own the bike and already paid for it once. That’s an open wound, not a one-time hit. It reopens every year until something changes about who’s actually signing up. Put plainly: $47 billion lost from the peak, $2.5 billion of it gone in a single day in January 2022, and $148 million a year still leaking out underneath. Three separate clocks. Keep them straight and nobody can argue with the math. The Financial EvidenceHere’s a twist that makes this worse than a normal decline. The same year those subscribers walked away was also the first time in Peloton’s history it turned a real profit for the whole year. A company can shrink and still profit for a while, usually by cutting costs faster than sales fall. It can’t do both forever. Here’s what actually happened, in real dollars. In December 2020, weeks before Peloton’s stock hit its all-time high, the company spent $420 million to buy Precor, a fitness-equipment maker with real factories. This is the manufacturing deal Ladd talks about: Peloton wasn’t buying a name, it was buying the ability to build a lot more bikes, fast. By early 2022, Peloton’s inventory, finished bikes and treadmills sitting in warehouses or stuck in shipping, had grown to $1.4 billion, up from $937 million a year earlier. Hundreds of millions of extra dollars in product nobody was buying. In the three months ending March 31, 2022, Peloton took a $182 million write-down, meaning what it owned was suddenly worth far less than it paid. The company’s own stated reasons: falling demand, higher costs, a dropping stock price, the exact thing Ladd says he warned about. It gets worse. Peloton had already promised to buy about $550 million worth of parts from its manufacturers, based on demand that no longer existed, and had to cut that down to somewhere between $120 million and $280 million: more than double, in some cases more than four times, what it actually needed. By late 2022, Peloton tried to sell Precor, the company it had bought less than two years earlier. The offers came back so low that CEO Barry McCarthy said the price had dropped past what he called “a stupid line.” In February 2023, Peloton gave up and kept it. Add it up: Peloton bought a manufacturing company at the exact peak of its stock price to build more bikes, was writing off hundreds of millions within a year for building too many, then tried and failed to sell the same company before keeping it anyway. Every piece of that matches what Ladd says he predicted. The numbers don’t prove Ladd was right about what Foley should have done instead. But they leave almost no room to argue he was wrong about what was about to go wrong. How It StartedThe idea didn’t come from Foley struggling to get to a class. It came from watching his wife struggle to get into one. This was New York, 2011 and 2012, and boutique fitness, small, trendy workout studios, was having a real moment. Wellness culture in general was booming: juice cleanses, gluten-free, “clean eating,” a whole industry built around looking like you had your life together. SoulCycle sat right in the middle of that boom, already a favorite among celebrities and Wall Street types, hard to get into for the exact reason everyone wanted in. Foley’s wife, Jill, loved taking SoulCycle and Flywheel classes in New York City. The problem was booking a spot. Those classes filled up fast, and good instructors were basically impossible to get into on short notice. Foley noticed something else too: when people talked about those classes afterward, they weren’t talking about the bike. They were talking about the instructor and the music. That gave him an idea. If the real product was the instructor and the experience, not the bike itself, could you bring that experience into someone’s house? The idea actually came together on a Disney cruise, of all places, during a conversation with his brother-in-law, John Pleasants. The two of them worked out the basic idea: a live, streamed spin class you could take from home. At the time, Foley ran e-commerce for Barnes & Noble. He left that job in 2012 to start the company, and he didn’t do it alone. He brought in Tom Cortese, someone he’d worked with before, to help run things. An engineer named Yony Feng built the first working prototype using off-the-shelf parts, nothing custom, just enough to prove the idea could work. Hisao Kushi came on as a cofounder too, and Graham Stanton joined early as one of the company’s first investors. The company was founded on January 3, 2012, in New York. Raising money was brutal. Foley has said he pitched the idea to more than 400 investors, and almost all of them said no. Wall Street understood spin classes. Wall Street understood tech startups. Nobody wanted to fund a company trying to be both at once: building expensive hardware, running a fitness studio, and writing streaming software, all at the same time. This was also just four years after the 2008 financial crash, when investors were still scared of anything risky, and hardware startups had a bad reputation. After nearly everyone with real money turned him down, Foley took the idea straight to regular people. In 2013, Peloton launched a Kickstarter campaign, a website where regular people can fund an idea before it exists, and raised just over $300,000 from 297 people willing to pay $1,500 upfront for a bike that didn’t exist yet. That crowdfunding round is what kept the company alive long enough to get noticed. The first real big-money investor didn’t show up until 2014, when Tiger Global put in $10 million. The company shipped its first real, internet-connected bike in 2014, the same year that first big check came in. Here’s what’s worth noticing about those first two years. Foley didn’t set out to build the future of fitness. He solved one problem, for one person: his wife couldn’t get into a SoulCycle class. That’s a real problem, and solving it is exactly how plenty of good companies get started. But solving a narrow problem for the person right in front of you, and building a business that still makes sense a decade later, are two different things. Foley built the first one. He never had to ask what his own idea would look like once the technology around it changed completely, because for most of the company’s first eight years, it didn’t have to. The Operational MistakesSome of these mistakes started years before the pandemic ever hit. Others are the pandemic-era bet Ladd’s thesis explains: betting demand would last forever, and buying manufacturing capacity because of that bet. Walking through each one shows how the earliest mistake set up every mistake that came after it. Mistake 1: Eight years, one product, while competitors built the rest of the home gym. Peloton was founded in January 2012. From then until the pandemic hit in March 2020, eight years, it shipped exactly one new kind of hardware: the Bike, starting in 2014, and the Tread, announced in January 2018. That’s the entire lineup for eight years. Meanwhile, other companies were already building the rest of the home gym. Tonal, a strength-training machine, shipped in August 2018. Hydrow, a rowing machine, shipped nationwide in spring 2019. Peloton didn’t ship its own strength machine, the Guide, until April 2022. It didn’t ship its own rowing machine, the Row, until December 2022. That’s three and four years behind, and only after the pandemic had already proven the category was worth entering. This wasn’t a company moving carefully and deliberately. It was a company that built one very good bike, then a decent treadmill, and spent eight years and hundreds of millions of dollars without using any of it to build out the rest of the category before its competitors did. Foley had a whole business plan built around one kind of workout, indoor cycling, right when the whole home-fitness market was about to split into a dozen different kinds of equipment. He didn’t just misread the pandemic later; years earlier, he’d already underbuilt the business the pandemic would eventually hand him for free. That idea, live instructor, streamed into your house, on a bike with a screen, was genuinely clever in 2012. Back then, the iPhone 4 was the newest phone in most people’s pockets. There was no real AI in everyday products. Streaming video into a home workout was still a new idea, not something everyone already had ten versions of. 2026 is a completely different world. Apps can build you a personalized workout plan for free, wearables track your entire body in real time without a subscription attached, and world-class instructors stream for a few dollars a month, no $2,000 hardware required. The whole world Peloton was clever inside of in 2012 has been rebuilt from scratch, and now everyone already has ten versions of it. And Peloton’s core idea hasn’t moved with it. It’s still a bike, a screen, and a monthly fee, the same basic pitch from 14 years ago, while the world around it changed completely. There’s something else going on here too. People look for community, even the ones earning six figures and up. That’s part of why Ladd’s thesis holds up: once gyms reopened, people went back, not for better equipment, but for a room full of other people instead of a screen alone in a bedroom. Peloton could have won by building itself around that idea. It never did. Mistake 2: Locking in fixed capacity against a temporary demand shock. (”Fixed capacity” means Peloton built enough factories and staff to make a set number of bikes no matter what, even if demand later dropped. “Demand shock” means a sudden, temporary spike in how many people want to buy something.) By mid-2020, Peloton’s order backlog, all the orders it hadn’t shipped yet, had stretched into months, not weeks. On the earnings call for the three months that ended June 30, 2020, held on September 11, 2020, management told investors it was doubling production and warned that shipping times wouldn’t return to normal until 2021. Foley described the company as being “in building mode for the foreseeable future.” A new factory in Shin Ji, Taiwan, came online that December just to add more bike and treadmill capacity, on top of the factories Peloton already owned, since most of its products by this point were built in Peloton’s own factories instead of ones it paid other companies to run. Here’s why this matters: manufacturing capacity isn’t something you can just turn down later, the way you might cut a marketing budget. Once you sign contracts with suppliers, build factory space, and promise to buy parts months or years ahead of time, you’ve locked in a guess about the future as if it were a fact. The guess Peloton built around came from one specific, temporary thing: every gym in the country was closed at the same time. There was no version of the future where that stayed true forever, only a question of how long it would take to go back to normal. Peloton built and spent as if the answer was “a long time.” The $1.4 billion in finished bikes and treadmills sitting in warehouses by early 2022, and the $182 million write-down that followed, trace straight back to a decision made in September 2020, eighteen months earlier, built on a guess nobody checked against how pandemics actually end. Mistake 3: Announcing a US factory, delaying it, then cancelling it before it opened. In May 2021, Peloton announced its first US-owned factory, a $400 million project in Wood County, Ohio, called Peloton Output Park. It was supposed to employ around 2,000 people and open in 2023. The land alone cost Peloton roughly $6.2 million. The thinking, at the time, wasn’t crazy: rely less on factories overseas, build a “made in America” story into the brand, and get ahead of what leadership still believed was a growing market. The real problem was the same guess behind Mistake 2: that the demand the factory was being built for would still be there once it opened. It wasn’t a clean, single decision to cancel, either. The 2023 opening date slipped to 2024 as demand kept dropping through 2021. Then, on February 8, 2022, the same day Peloton announced Foley was stepping down as CEO, Peloton scrapped the whole project, before either opening date arrived and before real construction had even started. The land was later sold to First Solar in January 2024 for $33 million, a gain, on paper, of roughly $26.8 million over what Peloton paid for it. On the surface, that looks like Peloton actually made money on the land. But that number doesn’t count the money already spent building part of the factory, the planning, the hiring that had already started, the deals made with suppliers, all for a factory that never ran a single shift. It also doesn’t count the trust burned with local officials and a town that was promised 2,000 jobs and got none of them. A land sale can turn a profit. A mistake this size doesn’t get erased by a real estate deal. Mistake 4: Building its own delivery network, then tearing it down for an outside company. Alongside building factories, Peloton also built its own delivery and setup operation: warehouses, delivery crews trained specifically on Peloton equipment, and software to run it all, eventually reaching 16 warehouses at its peak. The stated reason was customer experience: a top-quality, in-home setup made Peloton feel premium, something a regular shipping company couldn’t easily match. That’s a fair argument. Owning your own delivery network can genuinely work when you’re shipping enough volume, steadily enough, to make owning it cheaper than paying someone else. On August 12, 2022, CEO Barry McCarthy announced Peloton was closing all 16 warehouses and handing delivery to outside companies, mainly XPO Logistics and J.B. Hunt. McCarthy said the switch would cut delivery costs roughly in half, and admitted delivery had “been a challenge.” Put those two facts together and it’s basically an admission: the network Peloton built to stand out on customer experience had gotten too expensive for how few deliveries were actually moving through it, and an outside company could do it almost as well for a lot less money. This wasn’t a small operational tweak. It was proof that the same bet behind Mistakes 2 and 3, that this much demand was here to stay, never showed up at the size needed to make owning a delivery network worth it. Line the last three mistakes up and they’re not three random stumbles that happened to land around the same time. They’re the same mistake, made three separate times, by three different parts of the company: manufacturing, real estate, and shipping. Each team had every reason to believe the same story leadership was telling investors, that this growth was permanent, not a short-term spike. Someone could have checked that story against how past pandemics actually ended, and caught it in any one of these three places before the money was spent. Nobody did. But the very first mistake on this list happened years earlier, and it’s arguably why the other three were even possible. A company that spent eight years building only one real product had nothing to fall back on except doubling down on that one product once demand spiked. Instead, it all showed up later as a write-down, a cancelled factory, and a shut-down delivery network, one after another, over about two years. The Paper TrailOpinions don’t hold up in an autopsy. Records do. Here is every lawsuit, recall, and complaint on file, in one place, with the numbers attached. The music lawsuit, before the IPO. (”IPO” means the day a company first sells shares to the public.) In March 2019, a group called the National Music Publishers Association sued Peloton for $150 million. They said Peloton played copyrighted music in its classes without paying for it. That September, the amount they wanted grew to $300 million. Peloton settled in February 2020. The terms were never made public, but Peloton signed proper licensing deals with the big music publishers afterward. This happened before every pandemic-era mistake in this piece. It shows a company that grew its main product, streamed classes with music, before it locked down the rights to that music. The Tread+ fight, the recall, and the penalty. On April 17, 2021, the government’s product-safety watchdog, called the CPSC, warned people to stop using the Tread+ around kids and pets. A child had died, and dozens of people were hurt. Peloton didn’t quietly look into it. It put out a press release calling the warning “inaccurate and misleading.” Eighteen days later, on May 5, 2021, Peloton completely changed its mind and recalled both the Tread+ and the Tread. On January 5, 2023, Peloton agreed to pay a $19 million penalty. The reason: it didn’t report the danger fast enough, and it kept shipping the treadmills even after announcing the recall. Two seat post recalls, two different bikes, two and a half years apart. On May 11, 2023, Peloton recalled about 2.2 million original Bikes, sold since 2018, after more than 35 people reported the seat post breaking and causing falls. Then, on November 6, 2025, Peloton recalled another 833,000 units, this time the Bike+, sold between December 2019 and July 2022, after three more reports of the same seat post problem, including two injuries. Same failure. Different bike. Showing up again almost three years later. This isn’t one bad batch of parts. It’s the same defect breaking twice, on two different products, after Peloton had already recalled it once. The Lululemon lawsuit. In November 2021, Lululemon sued Peloton, saying Peloton’s clothing line copied its designs. Peloton settled in September 2022 and agreed to stop selling those designs. A year later, in September 2023, the two companies announced an actual retail partnership. Peloton ended up doing business with the same company that had just sued it for copying. A lawsuit about who could even use the product. On February 10, 2020, a deaf woman named Kahlimah Jones filed a class action, a lawsuit representing a larger group of people like her, saying Peloton’s workout videos had no closed captions. She said that broke a disability-rights law called the ADA, plus a similar New York law. The complaint named the exact videos she couldn’t follow without captions. This one matters because Peloton’s whole product is video. Accessibility wasn’t built in from the start. The shareholder lawsuit. Filed in November 2021, this lawsuit said Foley and other executives hid how bad the extra-inventory problem really was, while they sold their own stock. The case got thrown out three times, most recently on August 27, 2026, when a federal judge said there was no proof anyone meant to trick investors on purpose. The judge did leave the door open for one more try. (What this means for how the company was run is covered in The Boardroom, next.) What ordinary customers say, no lawsuit involved. As of this writing, Peloton has a C+ rating from the Better Business Bureau. It also carries an official “Pattern of Complaints” warning, the BBB’s label for a business that keeps getting the same complaints without fixing what causes them. Over the past three years, Peloton has logged 602 BBB complaints: 354 about service or repair, 82 about the product itself, 64 about delivery, 32 about billing, 29 about customer service, 29 about sales and advertising, and 12 about orders. More than half of all complaints are about service and repair. That matches everything else in this piece: a company that built its hardware and delivery around guesses that didn’t hold up in real life. Put it all together and a bigger pattern shows up. This is a business that grew its content before locking down the rights to it, that fought its own safety regulator in public and backed down within three weeks, that recalled the exact same kind of failure on two different products years apart, that got sued by the brand it copied and by a customer it never made its product accessible to, and that customers, with no lawsuit or regulator involved, still rate C+ with an open complaints warning. None of this requires taking my word for it. Every piece here is a public filing, a recall notice, or a court record. Every item on this list is roughly the same shape: Peloton moved fast on what it wanted, and slow on what it owed. Rights. Safety. Accessibility. Honesty with customers. That’s not bad luck. That looks like a company that mostly fixes what it’s forced to fix, usually after it’s already been forced to. Records don’t lie. Parts 2 and 3 are where I put the rest of them. The BoardroomAn autopsy names the people. So let me name them. John Foley ran Peloton from its founding in 2012 through February 2022. The Precor decision and the Ohio factory decision both happened on his watch, as the person running the company at the time. In 2021, the same year Peloton signed the $420 million Precor deal, Foley’s total pay was $17.8 million, a 57% raise from the year before. Peloton’s own yearly report to shareholders showed the gap between Foley’s pay and the typical Peloton employee’s pay: 317 to 1. The typical employee earned $56,084. The person deciding whether to bet hundreds of millions on permanent pandemic demand was, that same year, paid over three hundred times what the average person building and shipping the bikes was paid. Here’s the setup that explains why nobody could stop any of this once it started. Peloton went public in 2019 with what’s called a dual-class share structure, meaning some shares are worth way more votes than others. That gave Foley and other insiders and directors about 60% of the company’s voting power. By early 2022, after the stock had lost most of its value, that share of the vote had actually grown to roughly 80%, not shrunk. No matter what the board or outside shareholders wanted, Foley and the people around him controlled enough votes to decide how fast things changed, or whether they changed at all. Watch what he and the people around him did with their own stock while defending that bet in public. Throughout 2021, while Peloton’s stock was still trading above $100 a share, not far off its all-time high of roughly $171, company insiders sold close to $496 million worth of their own stock. Foley sold $119 million starting in November 2020, mostly above $110 a share, and turned off his automatic selling plan on August 30, 2021, months before the crash became obvious to everyone. President William Lynch sold $105 million, including $72 million in February 2021 alone at an average of $144.95 a share. Cofounder Hisao Kushi sold $90 million. Chief product officer Tom Cortese sold $60 million. Chief operating officer Mariana Garavaglia sold $25 million. Even board member Karen Boone personally sold $20 million in February 2021, above $140 a share. I want to be fair here, because leaving this out would make the rest of this section one-sided. A shareholder lawsuit said Foley and other executives used inside information to time these sales while hiding how bad the extra-inventory problem really was. (Full case details are in The Paper Trail above.) A federal judge eventually found no proof anyone meant to trick investors on purpose. Legally, Foley and the others are clean. I’m not arguing otherwise. But being legal and being smart aren’t the same thing. The people deciding whether Peloton’s growth was real enough to justify a $420 million purchase and a $400 million factory were, at the same time, quietly turning a huge chunk of their own paper wealth into cash, near the top of the market. You don’t need proof of a crime to notice that the people making the bet weren’t risking their own money the way regular shareholders were. There’s also the question of who was actually on the board while these decisions got made. When Peloton signed the Precor deal in December 2020 and committed to the Ohio factory in May 2021, its board doesn’t appear to have had anyone with hands-on supply chain or manufacturing experience. The board’s first clearly supply-chain-focused member, Angel Mendez, didn’t join until February 8, 2022, the same day Foley stepped down as CEO. That timing says a lot on its own: the board approved a huge manufacturing plan without anyone at the table who understood how these plans fail, and the one person with that kind of experience only showed up once the money was already gone. None of this could get fixed quickly, either, even once outside investors started shouting. On January 24, 2022, an investment firm called Blackwells Capital, which owned less than 5% of Peloton, sent the board a public letter saying the company was “on worse footing today than it was prior to the pandemic,” and demanded Foley be removed and the company put up for sale. Two weeks later, Foley did step down as CEO. He didn’t actually leave, though. He moved into the role of executive chairman, kept his board seat, and kept his voting power. It took another seven months, until September 12, 2022, for him to leave the company completely. Whoever came next was inheriting a mess, not taking over a healthy company. Barry McCarthy became CEO on February 9, 2022, straight from being the chief financial officer at Netflix, then Spotify, not a manufacturing background either. But that wasn’t the job anymore. The job was cutting. On his way out, Foley had already put his name on a plan to cut 2,800 jobs and find $800 million a year in savings. McCarthy spent the next two years carrying that plan out: another 500 jobs cut in October 2022, the warehouse shutdown covered earlier, and cost after cost coming out of the business. It kept Peloton alive. It didn’t fix the real reason people were leaving. McCarthy announced he was stepping down himself on May 2, 2024, alongside roughly 400 more job cuts. Peter Stern, previously an executive at Apple who helped build Apple Fitness+, took over as CEO on January 1, 2025. He cut the workforce again in August 2025, and finally got Peloton to its first full year of profit in fiscal 2026. Three CEOs in four years, each one cutting deeper than the last: that’s its own kind of proof. The company never grew its way out of this. It shrank its way to a profit. Step back, and here’s the full picture. Every place that was supposed to catch this problem, and stop it, failed to. The board lacked the specific know-how to question the manufacturing bet before it was made. The executives making that bet were quietly reducing their own personal exposure to it in real time. The lawsuit meant to test whether that was disclosed honestly ended up finding no fraud, just very bad optics. And even after outside shareholders demanded the person responsible be removed, the way the shares worked meant he got to decide how much power to give up, and when. Nobody broke the law. The setup just never forced anyone to move fast, take responsibility, or lose anything personally while the mistakes kept piling up. The ClockHere’s my actual prediction, dated on purpose so it can be checked later. But first, a distinction worth being honest about: some of what follows is on the record, some of it is my own reading of that record, and only the last part is the actual guess. Blurring those three together is how a forecast starts sounding like a fact. I don’t want this one to. What’s on the record. Peloton’s paid subscriber base has fallen three straight fiscal years through 2026, with the company’s own guidance pointing to a fourth straight drop in 2027. The company is profitable right now only because it’s cutting costs faster than it’s losing subscribers. The whole company trades for roughly $2.2 billion, cheap enough to buy without a bidding war. Foley and other insiders still control most of the vote, meaning a deal doesn’t need to win over everyone else, just them. And this part isn’t hypothetical: in May 2024, CNBC reported that multiple private equity firms were already circling Peloton for a potential buyout, and that at least one had held talks with the company about taking it private. Forbes and PYMNTS independently confirmed the same reporting the same week. Nothing came of it. But it’s proof the kind of buyer I’m describing already exists, and has already looked. What I think that adds up to. A company cutting its way to profit instead of growing its way there is running down a fixed amount of runway. At some point there’s nothing left to cut, and the board has to choose: sell while the numbers still look decent on paper, or wait and watch the story fade. Cheap stock plus a small group controlling the vote is usually how that choice gets made quietly, through a buyout most outside shareholders never get much say in, not through a public collapse. The actual call. I don’t think Peloton goes bankrupt. I think it gets bought out and taken off the public stock market, by a private equity firm, a company that buys other companies using investor money, or another company looking for a cheap, still-money-making name. I’m calling it for 2028. Watch for the first real outside pressure that year: a new activist letter, a leaked internal review, fresh rumors of a sale, with an actual deal following not long after. If I’m wrong, here’s exactly how you’ll know: Peloton is still an independent public company, trading under its own name on the stock market, past the end of 2028. (That call isn’t only built from the evidence above. Part of it comes from a scoring system I run every Brand Autopsy through, and part of it is instinct built from the rest of my process. Both pointed to the same year without me forcing them to agree, which is usually when I trust a call enough to publish it.) I’d rather be wrong in public than vague in private. A prediction that can’t fail isn’t a prediction. It’s just an opinion wearing a date. This one can fail, and if it does, I’ll say so, in this same series, when it happens. The full breakdown behind that call, the six category scores, the churn model behind the subscriber numbers, and the live thread as the 2028 prediction either lands or fails, is in Parts 2 and 3, for the investigators. If you’re already in, you’ll get it there. If you’re not yet, here’s the deadline that matters: the shareholder lawsuit’s amended complaint is due by roughly the end of September 2026. I’ll be reading the filing the day it lands, and I’ll post it in the Telegram group before I write it up. That’s the next live moment in this investigation. That’s your reason to join. My Own Theory: The DiagnosisEvery Brand Autopsy ends with a diagnosis. I run each company through my own Unseen Billions framework: six categories, each scored 1 to 5, thirty points total. That’s my own framework, a judgment call, not a modeled probability. Peloton scores 21 out of 30. That puts it in the same range as Target and Macy’s, both with about a 40% chance of actually turning things around, nowhere near Sears, which scored 28 and actually went bankrupt. Here’s the shape of it without giving away the scorecard. Three of the six categories scored a perfect 5, the highest possible. One scored a 3. One scored a 2. And one scored a 1, the lowest score in the entire framework, the one that tells you whether there’s anything here worth saving at all. If you want to know which three scored a 5, which one scored a 1, and why, that’s in Parts 2 and 3 for the investigators. What follows here is the diagnosis in plain language, no scorecard required. The full breakdown, category by category, with the reasoning behind every score, goes to the people who are already in. Even if Foley had never bought a single factory, even if he’d read the pandemic perfectly and stopped production the day gyms reopened, I don’t think Peloton escapes this. The real problem isn’t that Peloton built too many bikes. It’s that the thing you’re left holding, once the emergency, the free time, and the closed gyms go away, just isn’t that great on its own. Think about what you’re actually signing up for. A gym gets you out of the house, around other people, with a locker room and someone spotting you on the bench press. Peloton keeps you alone in a bedroom, pedaling at a screen, by yourself, every single time. During lockdown, being alone was the whole point. The moment that stopped being true, a lot of the appeal went with it. That’s the real story behind the cancellation number from The Bill: people who already paid for the bike, already own it outright, still walking away from the monthly fee at a rate you don’t usually see on something people genuinely love using. That reboot moment already mentioned up top didn’t stay a joke online. Within days of the episode airing in December 2021, it was everywhere: headlines, memes, jokes about the bike itself. Peloton’s own team felt the need to respond within 48 hours with a parody ad bringing the character back to life. That response alone tells you the company knew it had a real problem. After two weeks buried in the filings, I’ve landed somewhere Ladd doesn’t have to go: I don’t believe in this product. I don’t mean the company’s ability to survive. It already found its way back to profit. I mean the actual thing you’re being asked to buy: a $2,000 machine that only works if you keep paying $49.99 a month, for a workout you could get, in some form, for free or for much less, in a hundred other places. Go back to the question this piece opened with: who is this actually for. Here’s my straight answer: nobody at the top can say, and you can’t run a subscription business forever on top of a customer you can’t even describe. That’s a hope, not a business model. There’s a reason nothing at Peloton gets fixed until the last possible minute, and it isn’t bad luck. Sears scored worst on this framework because its CEO pulled value out of the company while it died. Peloton’s story is different, Foley never did anything close to that, but the same instinct shows up in his 57% raise the year he bet the whole company on Precor. The full comparison, including what Sears’ Eddie Lampert actually did, is in Parts 2 and 3 with the rest of the scorecard. The same insiders who controlled the board through the crash still control enough of the vote today to decide how much changes, and when. A company can stall this long only when the people it should answer to have no real way to force the issue. The company’s social media presence tells the same story. During the pandemic, Peloton was a real cultural moment: memes, TV storylines, everyone talking about it. Now it barely registers. You don’t fix that with a better ad campaign. It’s what happens when a company was relevant for one reason, that reason ran out, and it never gave people a new one. If Peloton wants a real second chance, two things have to change, and neither one is a product tweak. First, that vote-control problem needs an actual fix: a board that can outvote leadership, not one leadership can always outvote. Second, Peloton needs to rethink where it looks for customers. It expanded into the UK and Canada in 2018, then Germany in 2019, all Western markets that already look like the US, and none of them became a real growth story. My own read: that’s not a coincidence. Europeans walk and bike more, so daily exercise is already built into getting around. Canada has a huge amount of land and a small population spread across it, not the dense, wealthy cities Peloton says its customer lives in. I think the Middle East and Asia would have been the better bet, Dubai, Riyadh, Hong Kong, Singapore, Mumbai, dense, wealthy cities Peloton has barely touched. Fourteen years mostly in one country, then three more that look just like it, isn’t a money problem. It’s an imagination problem. To be fair, Peloton isn’t standing completely still. In April 2026, it announced “Fitness With Spotify,” putting more than 1,400 Peloton classes directly inside the Spotify app. Here’s the part worth sitting with: this isn’t the $49.99-a-month Peloton membership. It’s Spotify’s own subscription, the one people already pay for to stream music, now also unlocking Peloton’s classes. Peloton is handing out, through someone else’s cheaper subscription, the exact content it otherwise charges its own members $49.99 a month for. There’s a strange bookend here too: back in 2019, Peloton got sued for streaming copyrighted music without the right licenses. Seven years later, it’s letting a music platform give away its paid content for free. Whether that grows Peloton’s business or quietly proves the classes were never worth a separate $49.99 fee on their own is a different question. This isn’t only a Peloton problem. It’s the whole playbook of selling an expensive machine and then charging forever for the thing that makes the machine worth owning. That playbook works exactly as long as the reason people bought in stays true. The day it stops being true, the monthly fee turns into a tax on regret. Any brand selling hardware plus a subscription should ask itself the same question this piece just asked about Peloton: what happens to us if the moment that created our customer ends? What I actually think happens next: Peloton doesn’t disappear. It just becomes something you used to hear about, the way nobody talks about Bowflex now except as a punchline, one of those late-night infomercial machines people bought, used hard for two months, and then quietly turned into a coat rack in the garage. Because here’s the thesis this whole piece keeps coming back to: Peloton didn’t misread the pandemic. It misread what the pandemic meant. Lockdown didn’t create a new kind of customer who wanted to work out alone in a bedroom forever. It trapped the old customer somewhere with no other option, and Peloton mistook the cage for a change of heart. That’s the free version. The story, the numbers, the diagnosis, the call. Here’s what you get when you upgrade. What You Get When You UpgradeI just told you Peloton gets taken private by 2028. That’s a specific, dated call, and I could be wrong. Parts 2 and 3 are where you watch it get tested in real time: the six category scores behind that number, the churn model that shows exactly how the runway runs out, and a live thread tracking every filing, every subscriber count, and every sign that the call is landing or missing, as it happens instead of after the fact. This isn’t a newsletter. It’s a front-row seat to the patterns that show up before companies fail, and the early signs that can save you from betting on the wrong one. When you subscribe, you get: 1. The full case behind the 2028 call (Parts 2 & 3). The whole scorecard: all six categories, every score, and why I gave each one. The churn numbers broken down year by year, so you can see where the bottom actually is and how it feeds into the buyout prediction. And you get to watch it keep unfolding: the lawsuit’s next filing, due by the end of September 2026, the updated BBB complaint count, the repair costs I couldn’t confirm yet, and whether 2028 actually comes true. I’ll tell you what really happens, not just what I’m guessing. 2. The full Brand Autopsy archive. Every autopsy already published. If you’re an investor, you’ll spot the warning signs before the stock tanks. If you run a business, you’ll know exactly where your own blind spots are hiding. 3. The Unseen Billions Pattern Report, 53 pages. Fourteen company autopsies distilled into a single framework. This is the cheat sheet for spotting collapse before it happens. 4. Every new Brand Autopsy for the next 12 months. The moment it drops, not weeks later behind the paywall. 5. The private Telegram group. This is where the real pattern-spotting happens, direct access to me, plus a community of investors, executives, and insiders tracking these patterns in real time. When a filing drops, a recall hits, or a subscriber number moves, it goes in the group first. You’re reading it as it happens, not waiting for the write-up. Who Parts 2 and 3 Are ForThis series is for anyone who’s ever watched a beloved brand fade and wondered how did no one see this coming. That’s genuinely everyone, and this isn’t a niche investigation. But three groups get the most out of it. Shareholders and investors. You watched $47 billion in company value evaporate, and roughly $496 million in insider stock sales happen on the way down. You deserve to see the pattern before the market prices it in next time, not after. Brand strategists. The six-category framework used to score Peloton here works on any company, including yours. If you’ve ever wondered whether your own brand has a clear answer to “what are you for,” this is the diagnostic. Executives and board members. Especially anyone sitting in a boardroom right now approving a manufacturing bet without anyone at the table who understands how those bets fail. Peloton’s board did exactly that. This is what it looks like from the outside, three years later. And everyone else too: employees, competitors, journalists, or just someone who bought a Peloton, considered one, or wants to know how a cultural moment turns into a coat rack in the garage. The pattern applies whether or not you have a stake in it. Subscribe now. Become an investigator. I’ll see you in the Telegram group when the filing drops. One last thing. Thank you to Brittain Ladd for sharing his research with me and letting me build this whole thesis on top of it. This piece doesn’t exist without him. Disclaimer: I am not affiliated with, employed by, or sponsored by Peloton Interactive, Inc. in any way. I have never worked for the company, and this piece was not requested, reviewed, or approved by Peloton. This is independent analysis and commentary based on public filings, records, and reporting, built through Editmybrand’s Brand Autopsy™ methodology, and it reflects my own opinions and forecasts, not statements of fact about anyone’s intent. SourcesPeloton’s own filings and releases
Regulators
Lawsuits
The 2022 collapse and leadership
The Spotify partnership Spotify’s own newsroom announcement and Peloton’s investor-relations release on “Fitness With Spotify” (April 27, 2026), with coverage from CNBC, Bloomberg, Variety, Axios, Billboard, and The Hollywood Reporter. Brittain Ladd Two dated, public Ladd LinkedIn posts are independently verifiable: a January 24, 2022 post, the same day Blackwells Capital publicly demanded Foley be fired and Peloton put up for sale, and a mid-February 2022 post reacting to the investor slide deck Blackwells published shortly after. The core thesis and reasoning attributed to Ladd throughout this piece came from research he shared with me directly; where I couldn’t independently verify a specific claim, date, or figure, the piece says so. The Unseen Billions scoring framework and the 2028 prediction are the author’s own proprietary methodology and forecast, not third-party data, and are labeled as opinion and forecast throughout rather than presented as fact. Brittain Ladd: the core thesis and reasoning in this piece attributed to Ladd came from research he shared with me directly, not from a specific public article. Two dated, public Ladd LinkedIn posts are independently verifiable and confirm he was engaged with this exact story in real time: a January 24, 2022 post, the same day Blackwells Capital publicly demanded Foley be fired and Peloton put up for sale, and a mid-February 2022 post reacting to the investor slide deck Blackwells published shortly after. The Unseen Billions scoring framework and the 2028 prediction: both are the author’s own proprietary methodology and forecast, not third-party data, and are labeled as opinion and forecast throughout the piece rather than presented as fact. You're currently a free subscriber to Unseen Billions™. For the full experience, upgrade your subscription.
|




 Posts





0 Comments